S&P500 Daily Action Areas & Price Targets 12/10/26
S&P500 Daily Action Areas & Price Targets 12/10/26
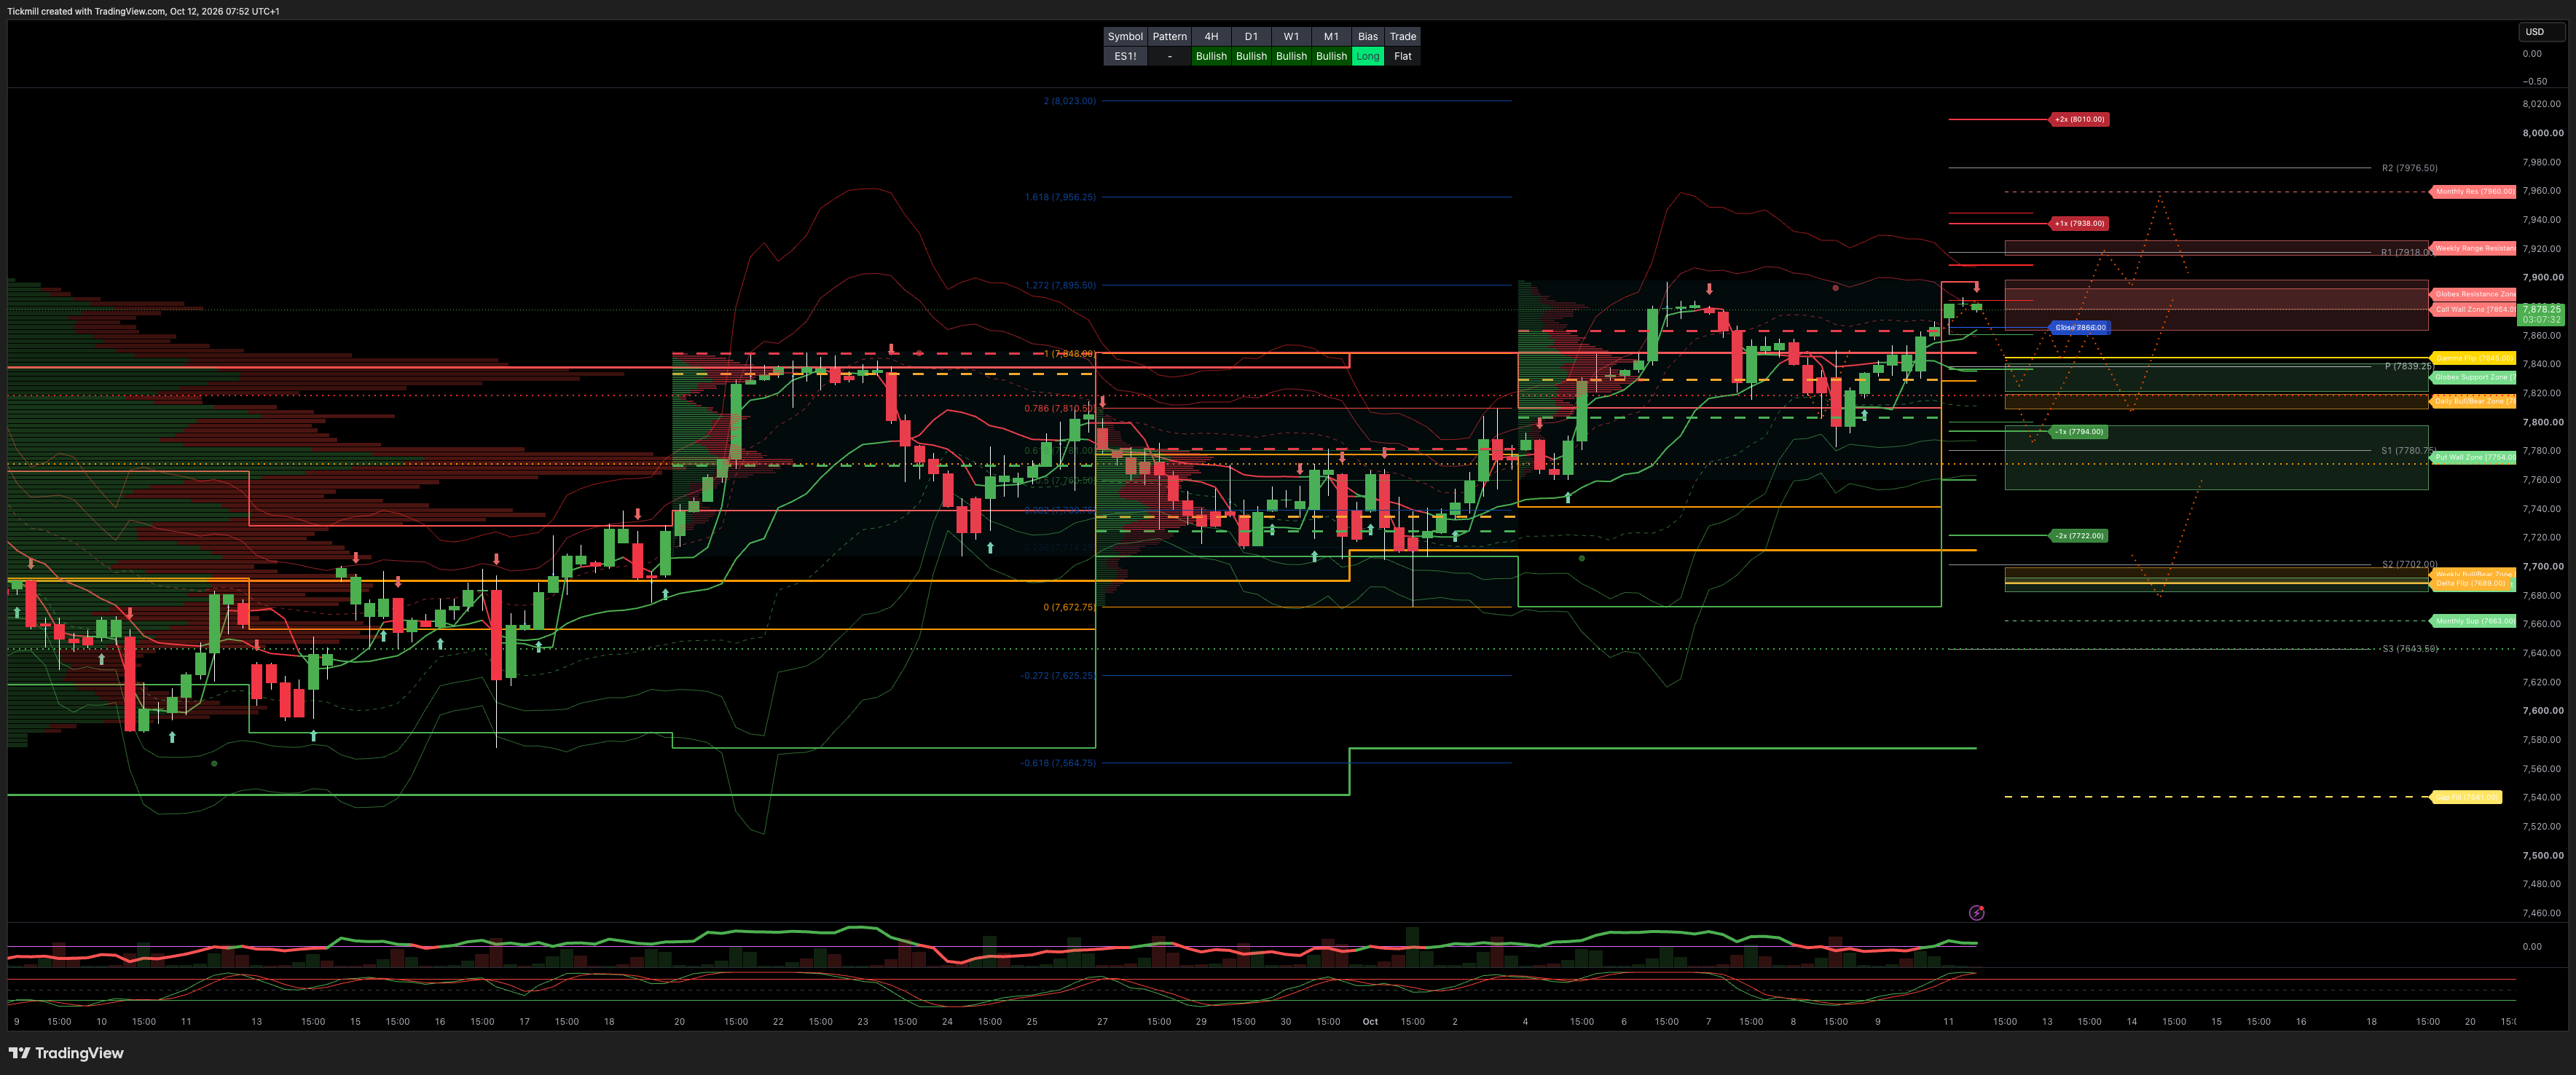
***QUOTING ES1!(Z CONTRACT LEVLES) FOR CASH US500 EQUIVALENT LEVELS, SUBTRACT POINT DIFFERENCE***
MONTHLY-WEEKLY& DAILY LEVELS
MONTHLY BULL BEAR ZONE 7440/7400
MONTHLY RANGE RES 7960 SUP 7663
WEEKLY BULL BEAR ZONE 7700/7690
WEEKLY RANGE RES 7926/16 SUP 7683/93
DAILY BULL BEAR ZONE 7820/10
GLOBEX RANGE SUP 7841/22 RES 7879/99
GAMMA FLIP 7845
DELTA FLIP 7689
CALL WALLS 7864/7893
PUT WALLS 7798/7754
UNFILLED GAPS 7541
DAILY STRUCTURE - BALANCE - 7897/7778
WEEKLY STRUCTURE - OTFH - 7778
MONTHLY STRUCTURE - OTFH - 7542
VIX BULL BEAR ZONE 17.7
VVIX-to-VIX ratio of 5.72 sits right in the historical "sweet spot" for market positioning, but its composition reveals a quiet shift in market dynamics
PRIMARY TRADES & TARGETS
LONG ON REJECT/RECLAIM OF THE DBBZ TARGET DAILY RANGE RES > ATH’S
***ADDITIONAL SETUPS & TARGETS HIGHLIGHTED ON THE CHARTS***
(I FADE TESTS OF 2 SIGMA LEVELS ESPECIALLY INTO THE FINAL HOUR OF THE NY CASH SESSION AS 90% OF THE TIME WHEN TESTED THE MARKET WILL CLOSE ABOVE OR BELOW THESE LEVELS)
SPX PUT/CALL RATIO 1.24 (The numbers reflect options traded during the current session.) A put-call ratio below 0.7 is generally considered bullish, and a put-call ratio above 1.0 is generally considered bearish.
JHEQX Upside cap (~7,920–7,950): Dealer gamma hedging at this call strike creates resistance, with market makers likely selling futures into strength and limiting volatility. Downside cushion (~7,270): If SPX drops 5% into Q4, long put gamma may force dealers to buy futures as the index falls, helping stabilize prices. Expiration: December 31, 2026. Strong pinning effects are likely near key strikes into year-end expiration.
DEC2025 OPEX to DEC2026 OPEX is 945 points giving us a range of [5889,7779]
Notes On Structure Implications
Balance: This refers to a market condition where prices move within a defined range, reflecting uncertainty as participants await further market-generated information. Our approach to balance includes favouring fade trades at the range extremes (highs/lows) while preparing for potential breakout scenarios if the balance shifts.
One-Time Framing Higher (OTFH): This represents a market trend where each successive bar forms a higher low, signalling a strong and consistent upward movement.
One-Time Framing Lower (OTFL): This describes a market trend where each successive bar forms a lower high, indicating a pronounced and steady downward movement.
GOLDMAN SACHS FICC & EQUITY TRADING DESK VIEWS
BREAKOUT RECAP, OPTION CHASE & SKEW DISCONNECT
Author: Brian Garrett (Goldman Sachs Managing Director, Global Banking & Markets)
THE TAKE: BREAKOUT PREVIEW & THE "FOBU" PERFORMANCE CHASE
Tuesday’s all-time high offered a stark preview of the upside convexity embedded in the market’s exceptionally low net exposure. As the S&P 500 broke through the long-standing 7,800 gamma wall, the first 90 minutes marked the busiest session on the trading floor in months. Aggressive spot-up / vol-up buying took hold as short-dated implieds notched higher, propelled by a cocktail of higher realized volatility, heavy call option demand, underweight benchmark positioning, clean gamma structures, and the realization that with only 57 trading sessions remaining in the year, being structurally underweight is an exceptionally crowded and dangerous trade.
Although the breakout failed to sustain and index implied volatilities ended the week near 5-year lows (with QQQ volatility standing out as particularly suppressed), the session laid bare the intense institutional Fear Of Benchmark Underperformance ("FOBU"). With marginal premium dollars increasingly incentivized to chase upside via call options rather than buy downside put protection, option markets are setting up for accelerated upside moves if quarterly earnings provide positive catalysts.
DESK FAVORITE TENOR: THE 30-OCTOBER EXPIRY BUCKET
When evaluating option tenors across book constructs, the index desk strongly favors the 30-October expiry bucket. This specific bucket allows investors to avoid paying elevated event premium for US midterm elections while capturing key Federal Reserve meetings, crucial economic data releases, and the vast majority of Q3 earnings reports (~65% of S&P 500 market cap reports by October 30).
Index / ETF | Out-of-the-Money Strike | 30-Oct Call Premium Cost (% of Spot) |
SPY (S&P 500 ETF) | 102.5% Call (~2.5% OTM) | 19 bps |
QQQ (Nasdaq-100 ETF) | 102.5% Call (~2.5% OTM) | 58 bps |
IWM (Russell 2000 ETF) | 102.5% Call (~2.5% OTM) | 62 bps |
VANILLA & LIGHT-EXOTIC TRADE IDEAS
Biotech Sector Rebound (
XBI): Positioning in biotech represents a compelling asymmetry, as the magnitude of the recent 8-week gross de-leveraging is nearly without historical precedent.Utilities Call Upside (
XLU): Utilities have rallied +4% over the past week following earlier desk calls, but remain well off their highs while street positioning remains max-short gamma.Long Defense / Short Non-Defense Industrials Pair: Buy Defense (
ITA) vs. Short Industrials ex-Defense (XLI). ITA is down -20% from August highs, providing industrial exposure backed by government demand, while XLI (-9% from August highs) remains a prisoner to interest rates and economic cycle risk.Brazil Dual Expression (
EWZ): Brazil faces a crucial end-of-month catalyst with active upside chasing. Desk prefers light-exotic structures playing for EWZ higher paired with a weaker Euro.Tax-Equivalent Muni Yields: Select municipal bonds are offering tax-equivalent yields matching historical long-run equity returns (10%+).
Non-AI Outperformance Options (Light Exotics): To express a market broadening without taking outright directional risk, outperformance options pay if the secondary asset outperforms the primary benchmark—even if both finish lower (e.g., SPX -10% vs. RSP -3% yields 700 bps of payout):
Dec 31 SPXXAI > SPX Outperformance Call (62 implied corr): 2.5% OTM priced at 2.75%; 5% OTM priced at 1.95%.
Dec 31 RSP (Equal Weight) > SPX Outperformance Call (62 implied corr): 2.5% OTM priced at 1.75%; 5% OTM priced at 1.15%.
PRIME BROKERAGE, ONE-DELTA & DERIVATIVES HIGHLIGHTS
Prime Brokerage Leverage Metrics:
Gross exposure expanded by +3.8 points for the week to sit at the 53rd percentile (1-year) and 80th percentile (3-year).
Net exposure lifted slightly by +0.5 points to 46.9, remaining severely depressed at the 2nd percentile (1-year) and 4th percentile (3-year).
The Long/Short market-value ratio declined to a 1-year low (1st percentile on a 5-year lookback).
One-Delta Flows & Tech Supply: Asset managers were small net sellers while hedge funds finished balanced. A single headline regarding AI model revenues brought out heavy supply in semiconductors and tech, illustrating nervous and forced length across the space.
Historical Dispersion & Skew Disconnect:
2026 Record Dispersion: The 3-month period ending Oct 8 registered a realized volatility spread (average stock vs. index) of 27, while the 9-month period registered 24, positioning 2026 as likely the most dispersive calendar year in history.
VIX vs. SPX Convexity Pricing: VIX upside convexity has gone aggressively bid while SPX downside convexity remains extremely offered. As the index desk notes: "It feels like there is a higher probability of VIX >25 than there is of SPX -2%".
Financials Earnings Setup (
XLF): Major financials have underperformed into earnings (XLF -6.5% from highs despite SPX record highs). The ratio of recent drawdown vs. earnings straddle is ~5x, making implied options moves exceptionally cheap ahead of prints (MS -20% from highs w/ 3.7% implied move; BAC -19% w/ 3.4% implied move; WFC -18% w/ 4.8% implied move).Small-Cap Upside Options (
IWM): RTY futures positioning sits at record shorts and IWM short interest is at record highs. With IWM volatility below the 10th percentile, under-positioned accounts can utilize low-cost upside calls to synthesize put coverage without liquidating linear exposure.Top AI Bottleneck — Power Up America Basket (
GSENEPOW): Desk identifies power generation as the single most under-appreciated AI bottleneck. TheGSENEPOWbasket remains the favored expression due to light positioning, normalized valuations, and strong fundamental drivers as Independent Power Producers (IPPs) sign long-term partnership deals with mega-cap tech hyperscalers.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!